
Florida Flood Insurance
Compare NFIP and private flood insurance options for your Florida home and find coverage that fits your property, needs and budget.
Flood Protection For Florida Homes
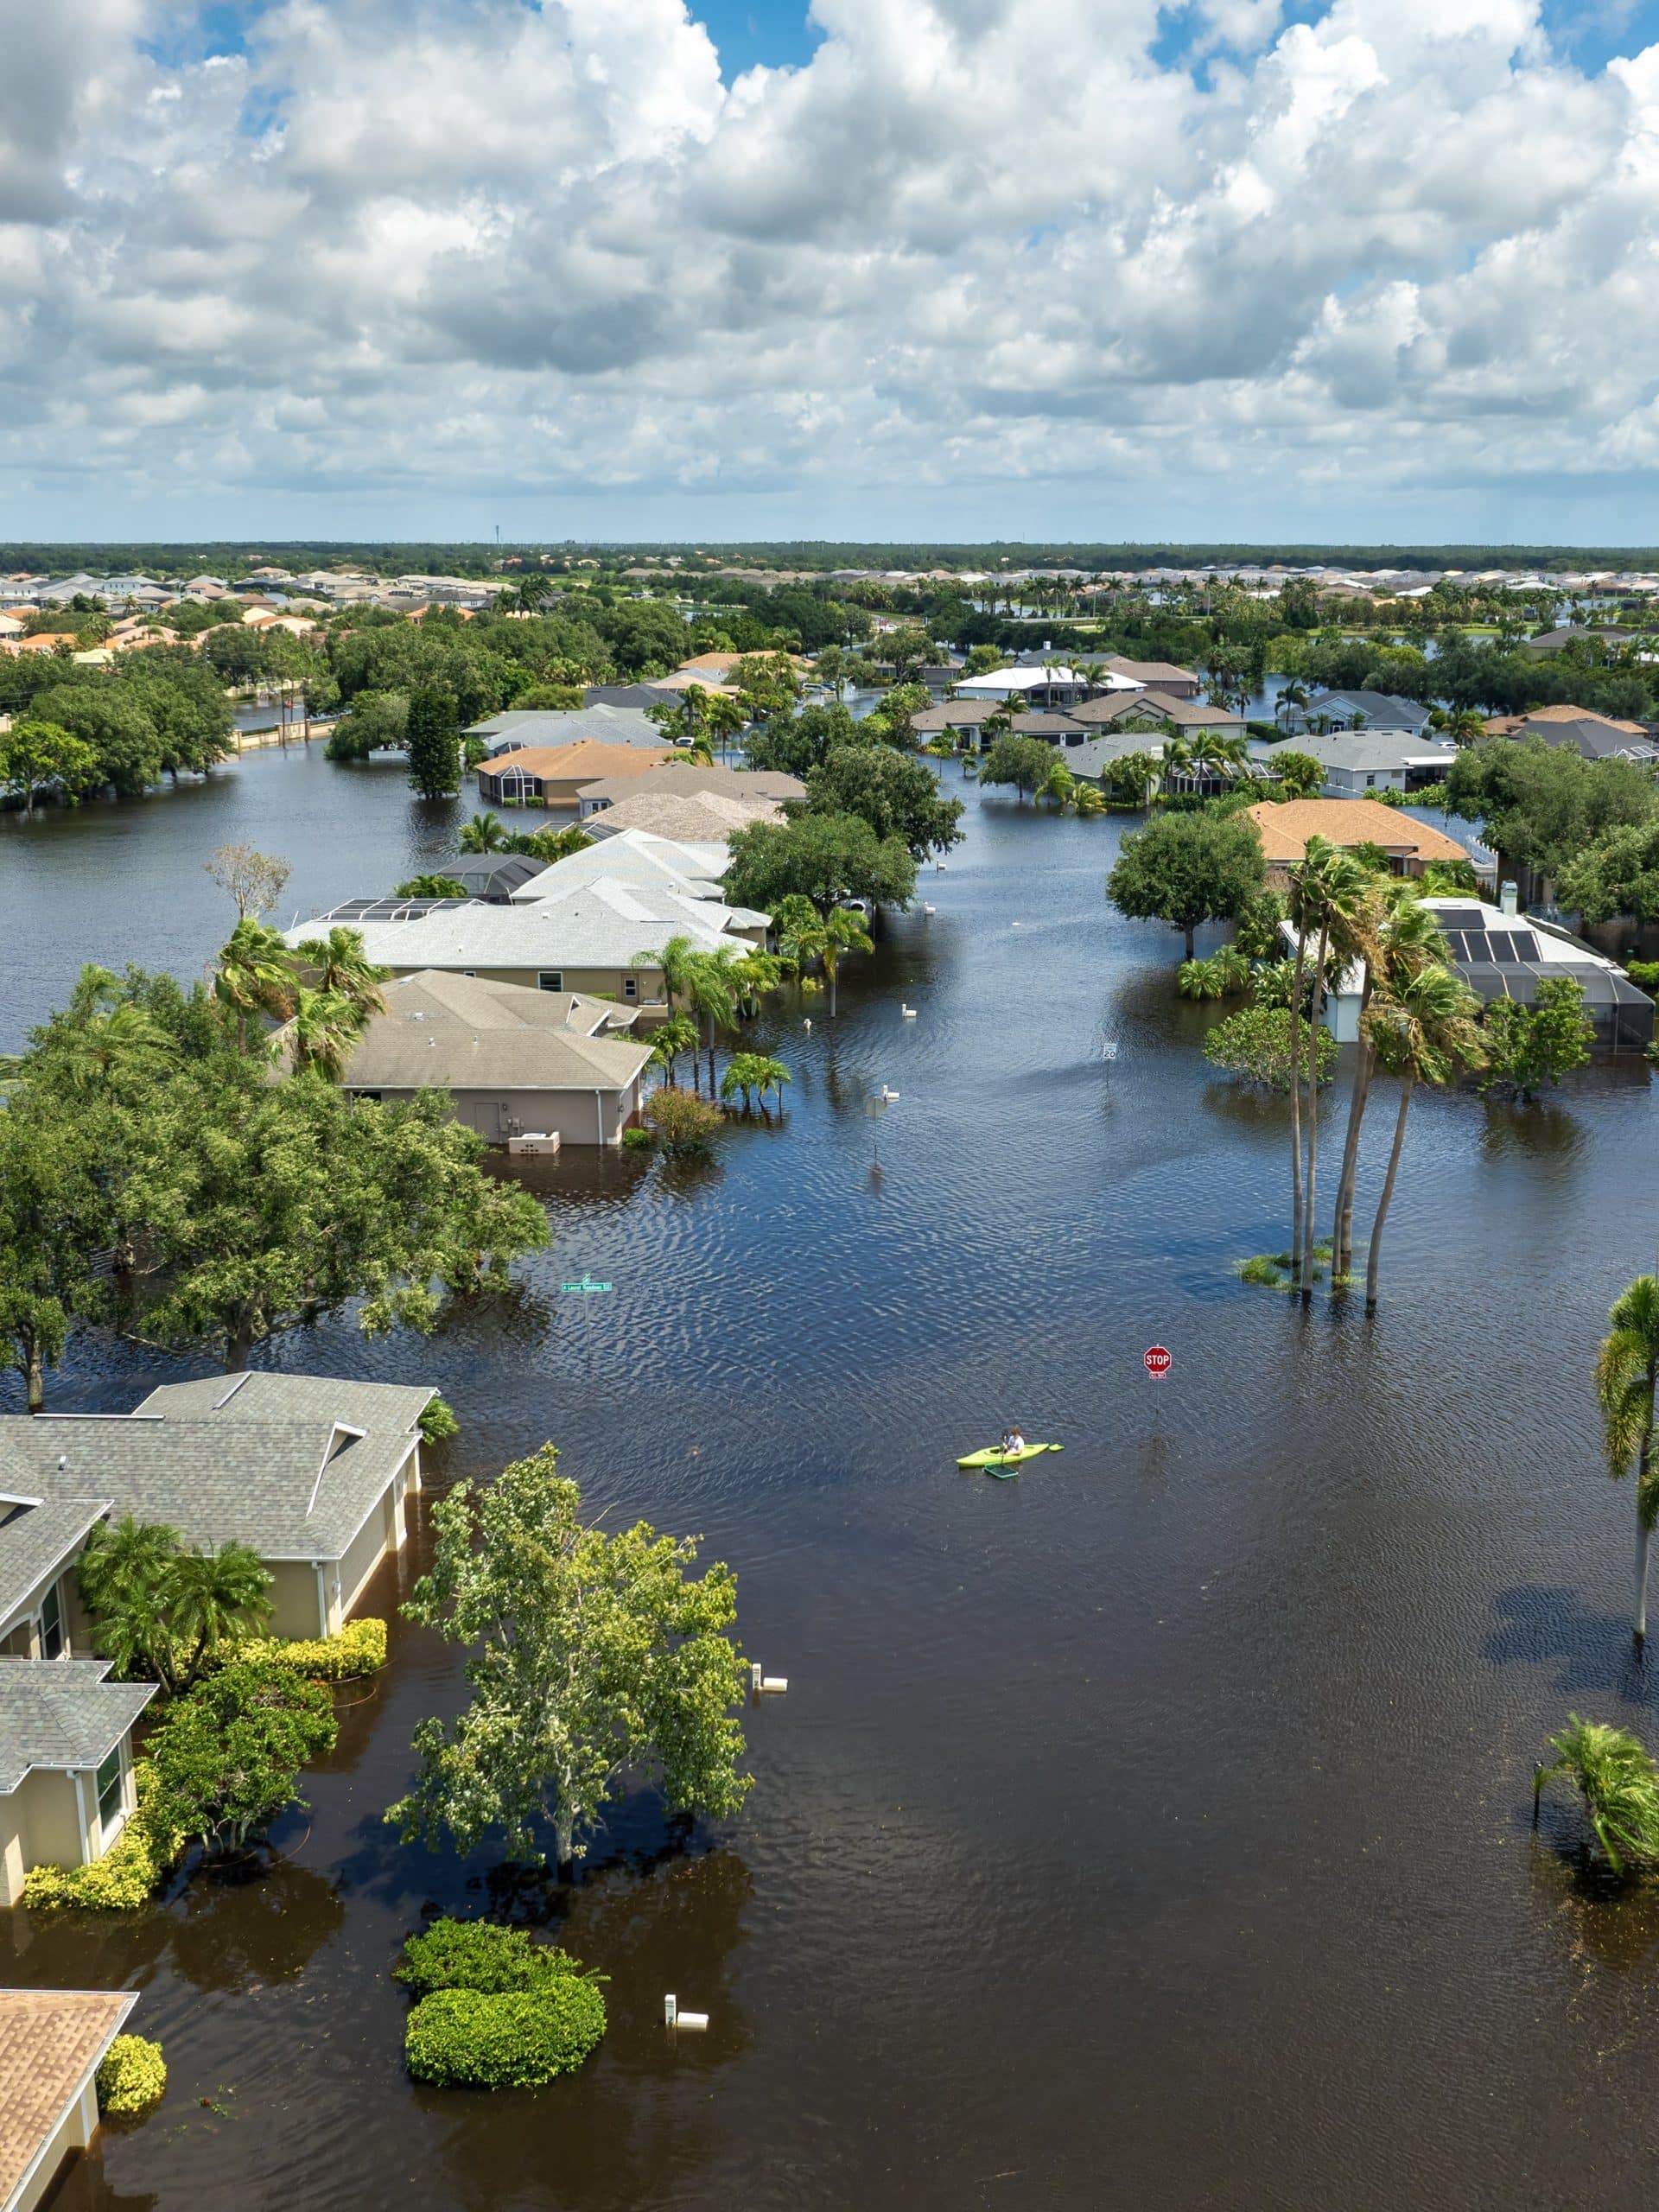
Florida’s flood risk extends far beyond beachfront property. Heavy rain, overflowing waterways, overwhelmed drainage systems and storm surge can all cause flooding, including in communities miles from the coast.
A 2024 analysis estimated that 23% of Florida properties face major-to-extreme flood risk over the next 30 years. That means serious flood exposure is much more widespread than many homeowners may realize.
And Florida gets plenty of water to test that risk. Florida receives the highest number of thunderstorms in the country and NOAA reports statewide precipitation is more than 53 inches a year.
Yet flood damage isn’t covered by your homeowners insurance policy. A separate flood policy can help protect your home and belongings from covered losses caused by rising water. At Brown Insurance Services, we help Florida homeowners compare available flood insurance options so they can choose protection that fits your property and budget.

More Flood Coverage Options
Explore flood insurance choices for your Florida home and choose coverage that matches how you want to be protected.

Quick Quotes, Real Advice
Get a fast quote and clear guidance on limits, deductibles, and what to expect before you buy.

Help Before and After a Loss
From renewal questions to claim-time support, our team is here when it matters most.
Why Brown Insurance?
Flood insurance isn’t one-size-fits-all, and we don’t treat it that way. As an independent insurance agency, we can help you compare NFIP coverage with available private flood insurance options rather than steering you toward a single carrier or policy type.
We look at both coverage and cost, because a lower premium only helps if the policy still provides the protection you need. Our team explains the differences in plain English, helps you understand limits and deductibles, and walks you through the tradeoffs so you can make an informed decision.
And our help doesn’t end when you buy a policy. We’re here for ongoing policy reviews, renewal questions and guidance if you ever need to navigate a claim.
What Does Flood Insurance Cover?
Building Coverage
Helps cover repairs to the structure of your home—including foundation elements, electrical and plumbing systems, HVAC equipment, and major appliances (like water heaters) damaged by flooding.
Personal Property Damage
Helps cover the cost to repair or replace belongings such as furniture, clothing, electronics, and appliances damaged by flooding.
Cleanup & Damage Mitigation
Helps cover removal of flood-damaged materials and cleanup-related costs (like tearing out and hauling away damaged items), depending on the policy.
Temporary Living Expenses*
If your home is unlivable after a covered flood loss, some policies may help with temporary housing and related living costs.
*Not available on all policies.
Rental Income / Loss of Use*
If you rent out all or part of your property, some policies may help cover lost rental income when the space becomes unlivable due to a covered flood loss.
*Not available on all policies.
Code Upgrades
Helps pay for certain required upgrades to meet current building codes after a covered flood loss, when applicable.
Who Needs Flood Insurance In Florida?
If your home is in a FEMA-designated Special Flood Hazard Area (flood zones A and V) and you have a mortgage from a federally regulated or insured lender, federal rules require flood insurance.
Your lender or insurer may also require coverage for a property outside those higher-risk areas. For example, Florida homeowners with certain Citizens policies also face separate flood insurance requirements.
However, a requirement is not the same thing as risk. Homes outside FEMA’s highest-risk flood areas can still flood from heavy rain, overwhelmed drainage systems and rising waterways. And because homeowners insurance does not cover flood damage, going without a flood policy means taking on that potential loss yourself.
Whether coverage is required or optional, we can help you compare available options and decide what level of protection makes sense for your property and budget.
Have Citizens?
Flood Insurance Is Required
As of Jan. 1, 2027, most Citizens Personal Residential policies that include wind coverage must also maintain flood insurance, regardless of the home’s value or whether it is located in a high-risk flood zone. Citizens currently lists condominium unit-owner policies, tenant contents policies and policies that exclude windstorm or hail coverage as exempt.
If that’s you, don’t wait until your policy is up for renewal. We can help you compare NFIP and available private flood insurance options so you can meet the requirement with coverage that makes sense for your home and budget.
Need Flood Insurance In Florida?
You Have Options.
Flood insurance doesn’t only come from the NFIP. Florida homeowners may also have access to private flood insurance, and each option has its own advantages. The best fit depends on your home, coverage needs, lender requirements and budget.
NFIP Flood Insurance
- Backed by the federal National Flood Insurance Program
- Standardized coverage and policy terms
- May qualify for local Community Rating System discounts
- Typically includes a 30-day waiting period*
- $250,000 in building coverage / $100,000 in contents coverage (for single-family home)
* Waiting period is waived when policy is purchased in connection with a mortgage closing.
Private Flood Insurance
- Offered by private insurance carriers
- May provide higher limits or additional coverage features
- Deductibles and pricing can vary by carrier
- Waiting periods may differ from the NFIP
- May satisfy lender requirements when the policy meets applicable standards
At Brown Insurance Services, we compare available NFIP and private flood insurance options so you can see the tradeoffs clearly and choose the coverage that makes the most sense for your property.
The Flood Insurance Protection You Need
Flooding is the most common natural disaster in the United States. From coastal storms to inland flooding, proper flood coverage protects your most valuable investment.
Don’t wait until it’s too late, get the protection you need today.
What Does Flood Insurance Cost In Florida?
Even when purchased through the NFIP, flood insurance premiums depend on many factors:
- Your home’s elevation
- Distance from the coast, rivers, lakes or other flooding sources
- Building and foundation characteristics
- The cost to rebuild your home
- Coverage limits
- Deductible choices
- Whether you choose NFIP or private flood insurance
- The insurer’s rating and underwriting criteria
The price of coverage should also be weighed against the potential cost of going without it. According to experts, just one inch of water in a typical home can cause up to $25,000 in damage.
Because two Florida homes can have very different flood risk and pricing, the best way to know what coverage will cost is to get a customized quote. We can compare available NFIP and private options to help you find the right balance of protection and price.
Florida Flood Insurance Discounts
Where you live can affect more than your flood risk. Some Florida communities participate in FEMA’s Community Rating System (CRS), which rewards local floodplain-management efforts with discounts for eligible NFIP policyholders.
Depending on their rating, eligible properties can receive NFIP premium discounts ranging from 5% to 45%. That makes your community another factor worth checking when comparing flood insurance. We can help determine whether a CRS discount applies to your property and compare the resulting NFIP price with available private flood insurance options.
Flood Protection Starts Here
You don’t have to sort through Florida flood insurance options on your own. At Brown Insurance Services, we help homeowners compare available NFIP and private coverage, understand the differences, and choose protection that fits both the property and the budget.
Whether you need flood insurance for a lender or Citizens requirement, or you simply want to protect your home from a risk your homeowners policy doesn’t cover, we can help you find the right place to start.
And it pays to shop before you need the coverage. New NFIP policies typically have a 30-day waiting period, with certain exceptions, so waiting until a storm is approaching may be too late.
What Our Clients are Saying
Flood Coverage For
All of Florida

Florida Flood Insurance FAQs
Get answers to the most common questions about flood insurance and how we can help protect your biggest investment.
There isn’t one standard price for flood insurance in Florida. Your premium can depend on your home’s location, elevation, building characteristics, replacement cost, coverage limits, deductible and whether you choose NFIP or private coverage.
Because pricing is specific to the property, the best way to know what you’ll pay is to compare actual quotes. We can shop available options and help you balance protection with price. You can also learn more in our Florida flood insurance cost guide.
Yes. We encourage all homeowners to get separate flood insurance coverage, because homeowners insurance does not cover flood damage. Flood insurance is a separate policy designed to help protect your home and belongings from covered losses caused by rising water.
Even if your lender doesn’t require flood insurance, having coverage can keep a flood from becoming a major out-of-pocket expense.
Not for every homeowner. Flood insurance is generally required for homes in a FEMA Special Flood Hazard Area when the mortgage is subject to federal flood insurance requirements. Your lender may also require coverage in other circumstances.
Citizens has its own requirements. As of Jan. 1, 2027, most Citizens Personal Residential policies that include wind coverage must also maintain flood insurance, regardless of the home’s value.
Even when coverage isn’t required, it can still be a smart way to protect your home from a loss your homeowners policy doesn’t cover.
There are advantages to both, and you don’t have to assume one is automatically the better choice. NFIP policies offer standardized federal coverage and may qualify for community discounts, while private insurers may offer different limits, deductibles, pricing and coverage features.
We can compare available NFIP and private options side by side so you can see what works best for your property and budget.
New NFIP policies typically have a 30-day waiting period, but there are exceptions. For example, there is generally no waiting period when qualifying coverage is purchased in connection with making, increasing, extending, or renewing a mortgage.
Private flood insurance may have different waiting periods depending on the carrier. That’s one more reason to shop early rather than waiting until bad weather is on the way.
Possibly. Many Florida communities participate in FEMA’s Community Rating System, which rewards local floodplain-management efforts with discounts for eligible NFIP policies.
Depending on the community’s CRS class, those discounts currently range from 5% to 45%.
We can help you check whether a community discount applies to your property and compare the resulting NFIP option with available private coverage.
Zone X means FEMA considers the property to have lower mapped flood risk, not zero flood risk. Heavy rain, drainage problems and rising waterways can still cause flooding in Zone X.
A lender may not require flood insurance simply because your home is in Zone X, but that doesn’t mean coverage has no value. It’s worth seeing what protection would cost before deciding whether to take that risk on yourself.
Don't Get Caught In Disaster Without The Right Insurance
Don’t take chances when it comes to your home.
Make sure you’re protected to the fullest with flood insurance.